Home Loans for Self-Employed Individuals: Who Can Apply and How?
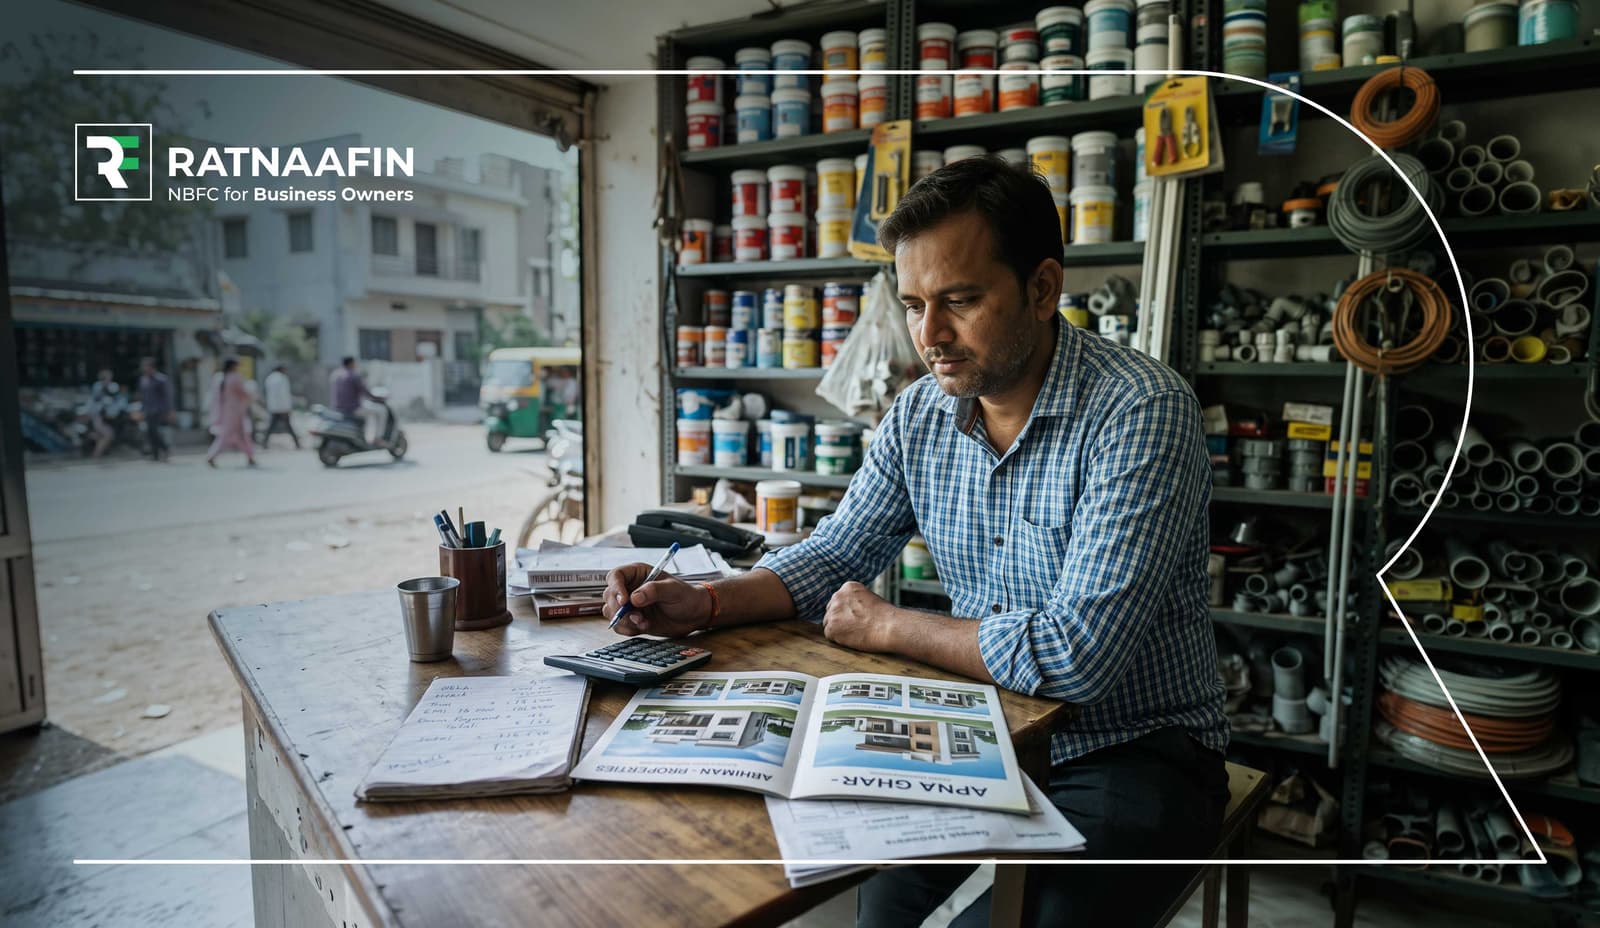
Running your own business gives you financial independence, but it can also make getting a home loan feel more challenging. The good news is that lenders today offer several home-loan options for the self-employed, including business owners, freelancers, consultants, doctors, lawyers, and professionals. With the right documentation and stable income, a home loan is well within reach the key difference is that lenders assess your income from tax returns and bank inflows rather than a salary slip.
Can Self-Employed Individuals Get a Home Loan?
Yes. Banks and housing finance companies provide home loans to self-employed applicants who meet the lender's eligibility requirements. While salaried employees submit salary slips, self-employed borrowers are assessed on business income, financial stability, tax returns, and repayment capacity. In practice, most lenders average your net profit from the last 2–3 years of ITRs and add back non-cash items like depreciation to estimate serviceable income.
Lenders consider consistent earnings, credit score, business continuity, and existing obligations before approving the loan.
Home Loan Criteria for Self Employed
Understanding the home loan criteria for self employed applicants can help you improve your chances of approval. Although requirements vary between lenders, the common criteria include:
- Minimum age of 21 years at the time of application.
- Stable business or professional practice, typically for at least 2–3 years.
- Consistent income reflected through Income Tax Returns (ITRs).
- Good CIBIL score, preferably 750 or above.
- Healthy bank account transactions and cash flow.
- Acceptable debt-to-income ratio.
- Property that meets the lender's legal and technical verification.
Meeting these requirements significantly increases the likelihood of faster loan approval.
Documents Required
When applying for a home loan for self employed, lenders generally ask for:
● Identity proof (Aadhaar, PAN, Passport, etc.)
● Address proof
● PAN card
● Income Tax Returns for the last 2–3 years, ideally with computation of income and Form 26AS
● Business proof (GST registration, Shop Act licence, Partnership Deed, etc.)
● Bank statements for the previous 6–12 months
● Profit & Loss Statement and Balance Sheet (where applicable), preferably CA-certified or audited
● Property documents
Submitting complete and accurate documents helps speed up the verification process.
Home Loan Options for Self Employed
Today, borrowers have multiple home loan options for self employed professionals. These include:
1. Standard Home Loan
Suitable for purchasing a ready-to-move or under-construction property.
2. Home Construction Loan
Ideal if you already own land and wish to build a house.
3. Home Extension Loan
Designed for expanding your existing home by adding extra rooms or floors.
4. Home Improvement Loan
Used for renovation, repairs, or interior upgrades.
5. Balance Transfer
Allows you to transfer your existing home loan to another lender offering lower interest rates or better terms, often combined with a top-up loan for additional funds at home-loan rates.
Choosing the right option depends on your financial goals and property requirements.
Why Rates Can Differ for the Self-Employed
Because business income can fluctuate, some lenders price self-employed home loans slightly higher than salaried ones, or ask for a marginally larger down payment. A strong credit score, clean ITRs, and a longer business track record are the levers that close this gap so it pays to get your paperwork in order before applying.
Tips to Improve Home Loan Approval
If you're applying for self employed home financing, these steps can strengthen your application:
- Maintain a high credit score by paying EMIs and credit card bills on time.
- File Income Tax Returns regularly.
- Keep business and personal finances separate.
- Avoid taking multiple loans before applying.
- Maintain healthy bank balances and consistent business income.
- Apply for a loan amount that matches your repayment capacity.
- Consider adding a co-applicant to improve eligibility.
Why Self-Employed Applicants Face Additional Checks
Unlike salaried employees with fixed monthly income, self-employed borrowers may have fluctuating earnings. Therefore, lenders carefully evaluate business performance, profitability, and long-term income stability before approving a house loan for self employed applicants.
This additional assessment is meant to determine repayment capacity rather than discourage entrepreneurs or professionals.
Common Reasons a Home Loan Gets Rejected
Even well-prepared applicants can be turned down, so it helps to know the usual culprits: low or inconsistent income on your ITRs, a weak CIBIL score or missed EMIs, too many existing loans (a high debt-to-income ratio), a short or unstable business track record, or legal and title issues with the property. Addressing these before you apply markedly improves your chances of approval.
Final Thoughts
Getting a home loan as a self-employed individual is no longer difficult if you keep your finances stable and your documentation in order. Whether you're a business owner, freelancer, or independent professional, there are options to suit different needs. Before choosing a lender, compare not just interest rates and processing fees but also how each one assesses self-employed income that single factor often decides how much you're approved for.
Understanding the criteria and preparing your documents in advance can help you secure faster approval and move one step closer to owning your dream home.