Home Loan vs Construction Loan: Which One Should You Choose?
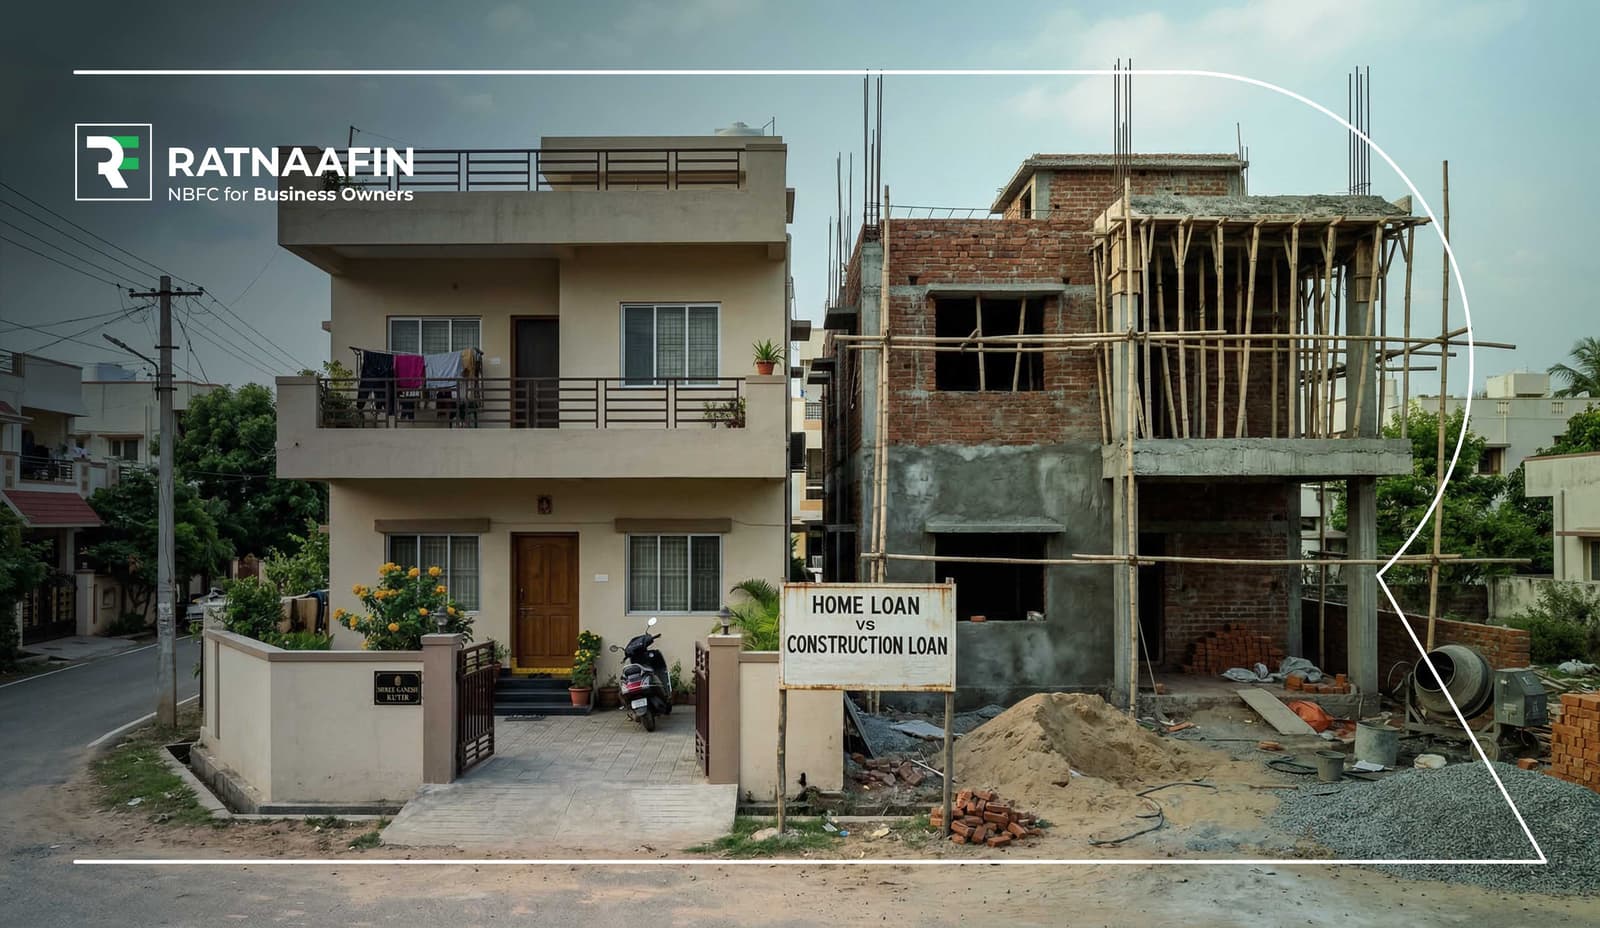
Home and construction loans serve their intended purpose. A home loan is also known as a mortgage, is created specifically for buying a ready-to-move home. Whether you are buying a house, villa, or apartment, a home loan lets you cover the cost of property for a longer duration of time, making ownership of a home more accessible.
However, a construction loan is made for those who want to build their home from scratch. If you have a vision for your dream home and a plot, then a construction loan can offer the necessary financing to meet the costs related to the construction process, including labor, permits, and materials.
What Is A Home Loan?
A home loan is a long-term loan used to purchase an entirely constructed residential property. It is best to purchase a ready-to-move-in home, condo, or townhouse.
When To Use A Home Loan?
- You need predictable monthly EMIs.
- When you want to buy a pre – owned or new home.
- If you are planning to occupy or rent any property quickly.
Key Features Of A Home Loan
- Your property will act as collateral.
- Lower interest rate compared to a construction loan.
- Longer tenure (up to 30 years).
- Variable or fixed interest rates.
- Installment begins immediately after disbursement.
What Is A Construction Loan?
It is a short-term loan that funds the building of a home from scratch or any major renovation on an existing property. This loan is disbursed in stages, mainly based on the progress of construction.
When Should You Use A Construction Loan?
- When you are doing a major teardown or big renovation.
- You own a piece of land or are planning to buy a piece of land and construct a home.
- If you want complete control over layout, design, and materials.
- You are hiring a builder or any contractor for new construction.
Key Features Of A Construction Loan
- Funds for construction are released in phases known as drawdowns.
- As compared to a home loan for construction of house, this loan have higher interest rate.
- The loan is of short term, i.e., 6 months to 2 years.
- You have to pay interest-only payments during the construction period.
- You can convert it to a home loan once construction ends.
Home Loan Vs Construction Loan: Which One Should You Choose?
Before getting any loan, it is important to understand both loan products individually. You can make an informed decision based on various parameters like:
1. Finances
As you know construction loan is disbursed in different phases based on the progress of construction. So, ask yourself if you can manage finances with a phased disbursement structure. If not, then you should consider purchasing a ready-to-move-in home with a home loan.
2. End Use
The choice of loan is obvious when it comes to the end usage. If you want to build your home from scratch, then a construction loan makes sense, but for a ready-to-move-in home, you should consider a home loan.
3. Tax Benefits
Before availing any loan, you should understand the applicable tax provision and determine which type of loan will help you to optimize your tax planning strategies.
4. Down payment
In the case of construction loans, the down payment is higher than that in a home loan. You should evaluate if your financial situation permits a high down payment and choose a loan accordingly.
Conclusion
Owning your own home is a significant milestone, and selecting the correct financing option is very important. By knowing the key differences in loans for building a house, you can make an informed decision that aligns with your financial capabilities and goals. If you still have doubt, which is best for you, hire the experts from Ratnaafin.